 Sunita Somvanshi
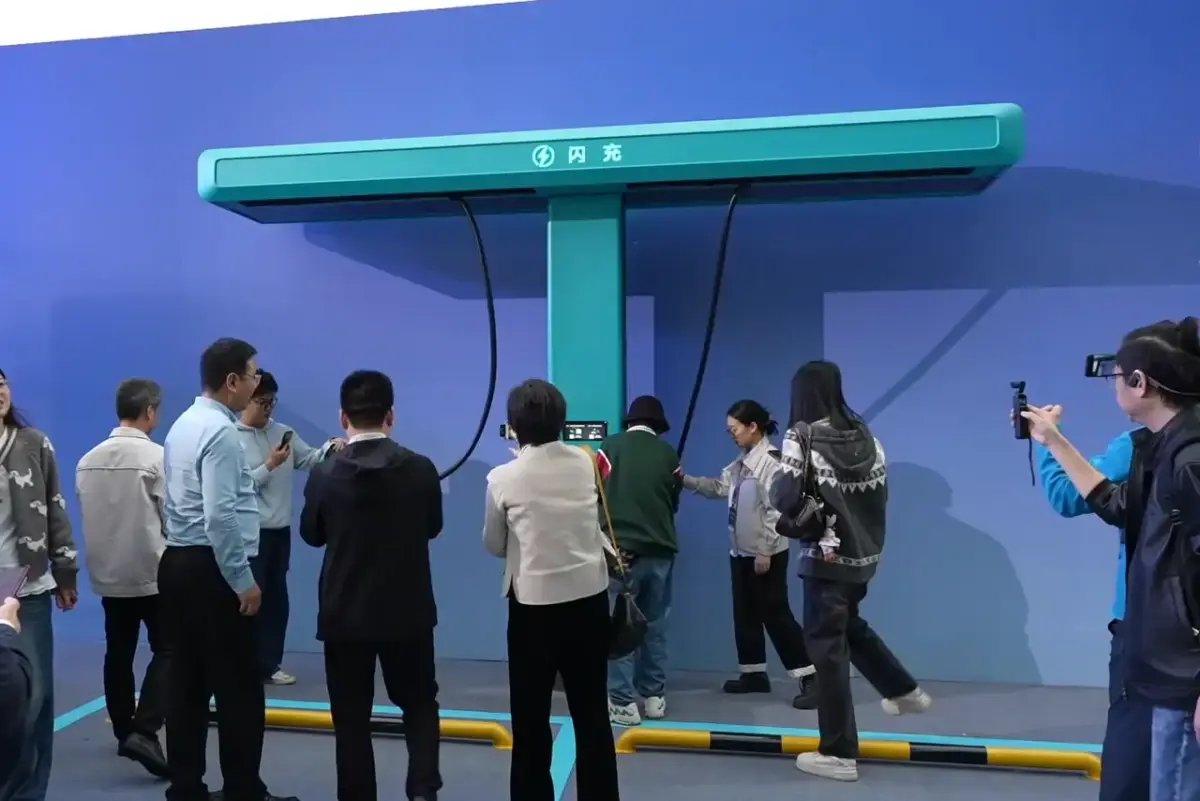
China's new five-year plan sets a target of 70% of new passenger-vehicle sales to be new energy vehicles by 2030. August 2026 data show NEVs already represented 60.6% of monthly new-car sales. That baseline changes how to read the target. China is not planning a shift from combustion vehicles to electric from a low baseline. It is managing an already-dominant category further while restructuring the industrial systems around it.
What China's Plan Covers
China's Ministry of Industry and Information Technology, along with eight other government departments, released the plan on September 11, 2026. The official target is 70% of domestic new passenger-vehicle sales to be new energy vehicles by 2030, with a separate 40% target for commercial vehicles.
The plan extends well beyond sales figures. It addresses battery and vehicle production capacity, autonomous driving deployment, charging infrastructure, battery-swapping networks, vehicle-grid interaction, energy consumption standards, industry consolidation, and international standards development. Nine departments are coordinating implementation through 2030.
The NEV Category
New energy vehicles include both battery-electric and plug-in hybrid vehicles. The target should not be read as 70% pure battery-electric. Both vehicle types count toward the NEV total. This distinction matters for supply chain planning, as plug-in hybrids require both battery systems and conventional drivetrains, while battery-electric vehicles do not.
How Close Is the Target
August 2026 CAAM data, as reported by Chinese government information services, shows NEVs reached 60.6% of China's monthly new-car sales. The September 2026 plan targets 70% by 2030, representing approximately 10 additional percentage points. This timeline is a significant push, but from a baseline where the category is already dominant in the market.
What The Plan Signals
For international suppliers of batteries, charging equipment, power electronics, software, and automotive components, the plan indicates where the world's largest vehicle market is directing industrial capacity and regulatory requirements through 2030. Tighter capacity controls, consolidation pressure on smaller manufacturers, and mandatory charging infrastructure expansion all point toward a more structured industry.
The autonomous driving component signals where China expects competitive advantage of its EV industry to shift — from basic electrification, which is already mature, toward connected and intelligent systems. For companies supplying into that market, the competitive bar is rising.
Closure
China's five-year plan targets 70% NEV penetration by 2030 across a broader intelligent-vehicle industry landscape. August 2026 data showing 60.6% NEV market share provides the current baseline. Monthly NEV sales figures provide the clearest short-term signal of whether the plan's trajectory is being met. Check back as monthly sales data releases.