 Sunita Somvanshi
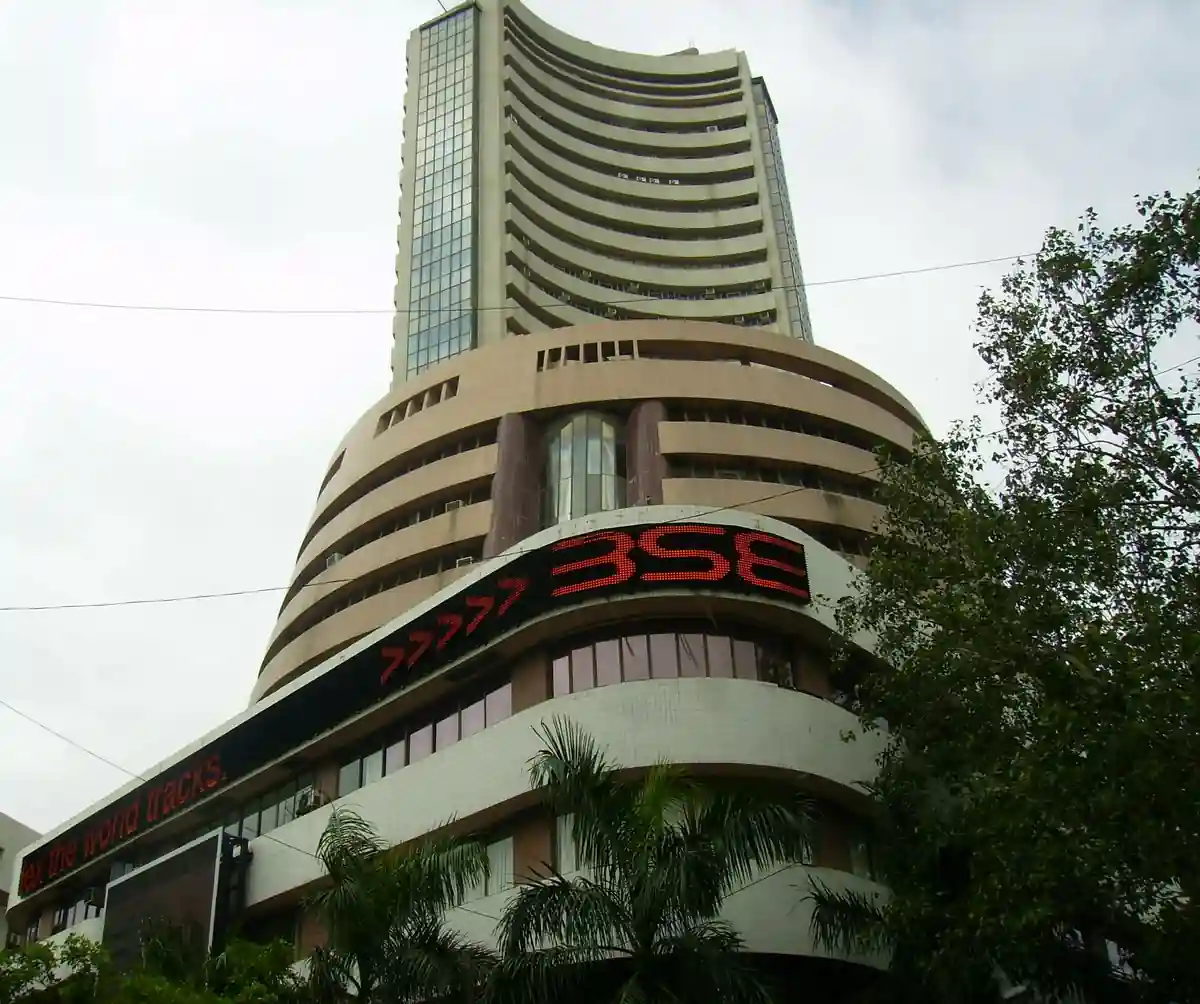
Indian equity markets broke an eight-week losing run on Monday, with Nifty 50 gaining 0.60% and Sensex up 0.66%, as concerns about aggressive US Federal Reserve tightening eased and crude oil prices pulled back from recent highs. The recovery is tentative. The Reserve Bank of India’s monetary policy decision lands on October 7, and TCS is among the first major IT companies reporting results for the September quarter.
Indian stocks had fallen for eight consecutive weeks, pressured by foreign institutional investors rotating capital out of domestic equities and into Chinese markets following Beijing’s stimulus announcements, while elevated crude oil import costs stoked concerns about India’s current account and the rupee. Net FII outflows from Indian equity markets exceeded ₹30,000 crore over the recent sell-off phase, according to NSE and BSE provisional trading data. Monday’s session provided partial relief as easing Fed rate expectations reduced the dollar’s appeal and crude prices pulled back, allowing buying interest to return.
Indian retail investors should stay prepared for continued near-term volatility despite Monday’s bounce. Rising crude oil import costs and ongoing FII capital outflows to stimulus-backed Asian markets continue to apply pressure on domestic equities. The RBI Monetary Policy Committee meeting runs from October 5 to 7, with Governor Sanjay Malhotra delivering the decision and guidance at 10am on October 7. With the repo rate currently at 5.25%, close to 60% of economists in a recent Reuters poll expected a 25-basis-point increase to 5.50%. TCS’s Q2 numbers will kick off the technology sector earnings season for the September quarter, and systematic investment plan contributors should consider maintaining current allocations through near-term volatility.
The RBI meeting is the week’s central event. The genuine question for markets is not just the rate decision itself, but the committee’s guidance on the economic outlook and inflation trajectory. Consumer price inflation trends and the rupee’s performance against the dollar will both colour how the policy statement is read by institutional investors.
The Real Market Movers Between October 5 and 8
The week’s other anchor is TCS’s Q2 FY2027 results, with the board meeting to approve earnings scheduled for October 8. Institutional brokerages have compiled consensus estimates for the Tata Consultancy Services quarter, and the IT sector — one of the Nifty’s largest components — will take directional cues from TCS’s revenue guidance and management commentary on US client spending. Any downward revision to forward guidance would renew pressure on IT sector stocks more broadly.
One factor that continues to limit the downside for Indian equities is domestic retail participation. Monthly inflows into equity mutual funds via systematic investment plans are running above ₹23,000 crore, according to AMFI data, providing consistent domestic participation even as foreign funds exit.
Whether Monday’s rebound extends into Tuesday will depend on the opening direction of Asian markets overnight and any fresh development in the Middle East that could push oil prices higher.
The RBI’s October 7 guidance statement and TCS’s Q2 numbers are the two events that will define how Indian markets trade through the rest of October.
—
HDFC Bank CEO appointment and stock-market reaction · Hormuz reopening proposal and oil-price risk · RBI Governor Sanjay Malhotra announcement · NSE FII/FPI and DII activity · TCS investor relations