 Sunita Somvanshi
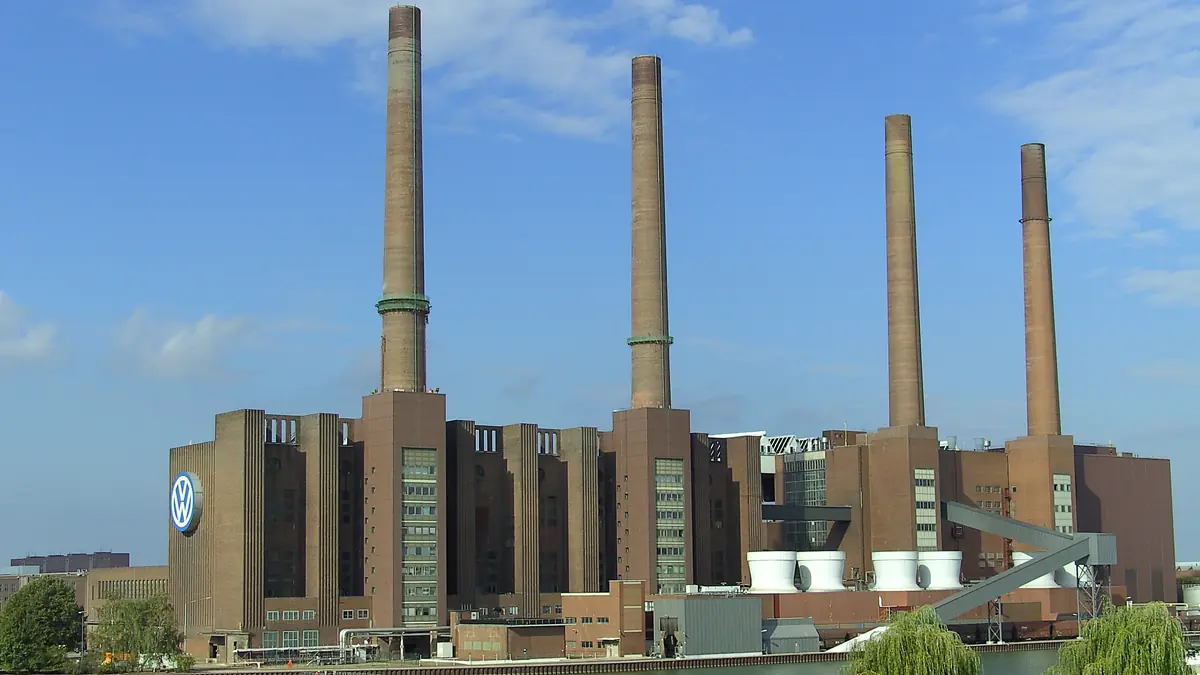
German car makers are cutting production hard. Auto suppliers are laying off thousands. If you’re buying German—cars, machinery, industrial parts—you’re watching prices climb and supplies tighten. Jobs are vanishing by the thousands every month across the manufacturing sector.
Germany’s manufacturing sector is in crisis. The country sheds 15,000 manufacturing jobs every month. Porsche operating profit collapsed 93% to €413 million. Mercedes operating profit fell 57% to €5.8 billion. VW net profit dropped 44% to €6.9 billion.
Germany’s economy contracted in 2023, was flat in 2024, and grew 0.2% in 2025—the first back-to-back contractions since the financial crisis. Year-to-date in 2026, it limps forward at 0.3–0.4% per quarter. The eurozone average was 1.1% in 2025. Germany managed half that. Manufacturing production fell 0.5% in June. Manufacturing output is 15% below its 2017 peak.
This doesn’t stay in Germany. Austria, Czech Republic, Hungary are embedded in German supply chains. When German factories slow, theirs slow. China’s second-largest market used to be Germany. It’s now ninth.
The reform package Merz bet everything on
Friedrich Merz took over as Chancellor in late 2024. He put together a 34-point reform package designed to restart hiring and cut the cost of employment. €10 billion in income tax relief for working families. Retirement age rising from 67 to 70. A new pension pillar for private savings. Workers can no longer call in sick by phone—medical certificates are now required from day one. Eight percent cuts across ministries to reduce bureaucratic drag.
The logic is straightforward: make hiring cheaper, make operations less expensive, push people to work longer. The government also allocated €500 billion for infrastructure and climate investment. Post-Ukraine, Germany had no choice—Russian gas shut off and the entire energy grid had to be rebuilt. The climate fund pays for solar, wind, grid upgrades, green hydrogen, battery storage. Energy independence was expensive. Stagnation was more expensive.
Unions resisted the sick-leave change. Business groups backed the package overall. The math looked sound on paper: cheaper to hire means more hiring, lower taxes means more capital for investment, longer working lives mean more tax revenue. The reforms were announced July 2026 and take effect in 2027. By autumn, confidence indicators showed improvement.
Why the data doesn’t match the optimism
Here’s where the trap appears: The ifo Business Climate index hit 88.8 in August 2026, the highest reading since before the pandemic. Executives are optimistic. But look at what’s actually happening.
Manufacturing production fell 0.5% in June 2026. Manufacturing output remains 15% below the 2017 peak. German exports to China are down 12% year-on-year in the first half of 2026. And the jobs keep vanishing—fifteen thousand manufacturing jobs disappear every month.
Why? The ifo index is a survey capturing what executives think will happen. The real data captures what is happening. Right now, executives are betting on Merz’s reforms. They think tax cuts and labor flexibility will work. But output, jobs, and exports are still crashing.
Manufacturing PMI came in at 54.3 in August, then 53.8 in September flash estimate. Both signal expansion—PMI above 50 means factories are growing. Meanwhile, the business confidence index says managers expect recovery. They’re betting Merz is right. They’re betting 2027 will be different. They haven’t bet with their hiring yet.
The gap between the ifo Business Climate at 88.8 and the manufacturing reality is the story. Fifteen thousand jobs lost monthly, manufacturing production falling, exports to China down 12%. This suggests executives believe in Merz’s reforms but haven’t seen proof yet. That’s either confidence before proof—or delusion.
Is Germany’s economy really broken?
Yes. Germany’s economy is broken—not that it’s failed, but that it can’t generate growth. It sheds 15,000 manufacturing jobs monthly. It contracted in 2023 and was flat in 2024. Major carmakers report 40%+ profit declines. This isn’t a temporary downturn. This is structural failure. Merz’s reforms are real. They may work. But they haven’t worked yet. The proof will come in 2027. The next quarter—Q3 and Q4 2026, Q1 2027—will show whether executives’ optimism matches reality. Germany’s recovery—or its continued stagnation—will determine wages and prices across Europe for the next five years.