 Sunita Somvanshi
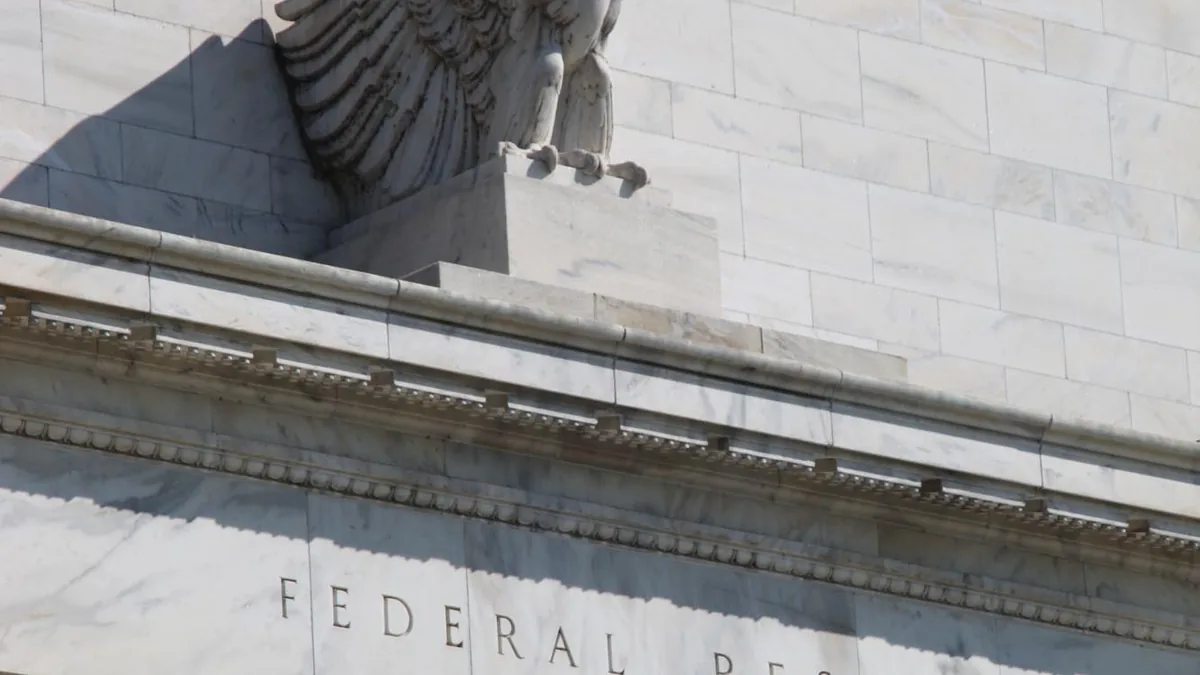
The Federal Reserve raised its benchmark interest rate by a quarter of a percentage point on September 16, 2026, moving the federal funds target range to 3.75–4%. The vote among Federal Open Market Committee members was 12–0—unanimous, with no dissent.
The Fed’s own statement explains the decision in direct terms: inflation remains elevated, and today’s policy action will support a timelier return to the committee’s 2% goal. The statement cites the Fed’s dual mandate of price stability and maximum employment as the framework for the decision.
The practical impact of this rate increase works through the financial system from the Fed’s overnight lending rate outward. Higher rates make it more expensive for banks to borrow money from each other, and those costs tend to be reflected in consumer and business lending—though the timing and amount vary by product and market. Credit card rates, which are typically variable and tied closely to the federal funds rate, tend to move quickly. Mortgage rates are influenced more by longer-term bond yields than directly by the Fed funds rate, but those yields often respond to Fed decisions as well. Variable-rate loans—including home equity lines of credit and some personal loans—typically move up within billing cycles. Fixed-rate products do not change, which is one reason refinancing decisions become more consequential when rates are rising.
What the FOMC statement actually says
The Fed’s September 16 statement is more measured than market commentary about it. The statement says job gains “have kept pace with the workforce, and the unemployment rate has changed little.” It also states plainly: “Inflation remains elevated.”
The statement notes the Fed’s dual mandate as the foundation for the decision and makes clear that future moves depend on incoming economic and financial data rather than a pre-set path. The committee can raise, hold, or cut at future meetings.
The 12–0 vote is notable because it represents a unanimous judgment among all voting FOMC members in support of the decision.
The implementation note released alongside the main statement sets the technical rates that define the boundaries of the new target range in practice, including the interest rate on reserve balances and the overnight reverse repurchase agreement rate.
What does the Fed rate hike mean for borrowers?
A higher federal funds target puts upward pressure on borrowing costs across the economy, though not immediately and not uniformly. Credit card rates are typically variable and tied to the federal funds rate. Variable-rate loans—including home equity lines of credit—adjust at similar speed. Mortgage rates are influenced more by bond markets than by the Fed’s overnight rate directly, but bond markets tend to respond to Fed decisions. Fixed-rate loans do not change for existing borrowers. Savers with high-yield savings accounts or money market funds may see some benefit, though returns depend on how institutions respond. The net effect depends on how much debt a household carries and at what rate, and on how much savings they hold.
The next FOMC meeting will determine whether the Fed pauses, continues raising, or signals a change in direction. The September statement makes clear that depends on economic data between now and then. Watch for incoming economic and financial data in the coming weeks—those are the inputs the committee has said will guide future decisions.