 Sunita Somvanshi
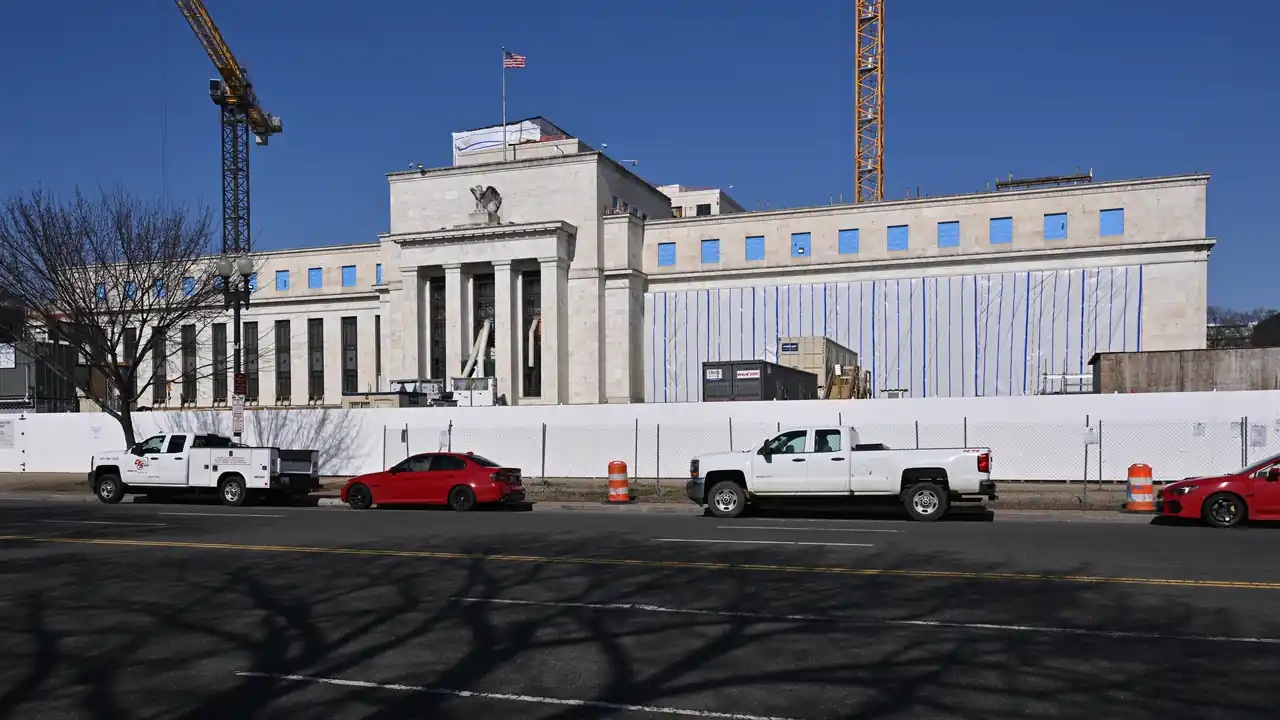
The Federal Reserve raised its benchmark interest rate by a quarter-point (0.25%) at its September 2026 meeting, marking the first increase since July 2023 as the central bank addresses persistent inflation. The decision raises the federal funds target range to 3.75%–4.00%. The immediate impact on household debt will vary depending on loan type, contract terms, and lender policies.
The Fed’s previous decision in July held rates steady at 3.50%–3.75%. Fed Governor Christopher Waller had publicly indicated on September 3 that an increase could be appropriate depending on incoming data. The September meeting confirmed that incoming data supported action. Future rate projections will depend on the September Summary of Economic Projections and press conference guidance, which analysts will examine closely.
This rate increase will affect borrowers with variable-rate debt differently depending on their loan terms. If you have a variable-rate mortgage, a home equity line of credit, or carry a balance on your credit cards, your costs may increase after your issuer applies the new index—timing varies by product, issuer, and contract. Existing fixed-rate loan contractual rates do not change with this decision; however, future refinancing or new borrowing costs will be higher.
What May Change for Your Wallet
Variable-rate credit cards typically track prime rate and may reset their interest rates within one to two billing cycles after a Fed increase, though issuer timing and terms differ. If you carry a $5,000 balance on a card charging 18% APR, your monthly interest cost is roughly $75. A 0.25% increase applied to the card’s APR would add approximately $1.04 monthly. Over a year, that’s $12.50 extra on that single card—for households with multiple cards or higher balances, the impact is proportionally larger.
Home equity lines of credit commonly track prime rate, but individual margins and adjustment terms differ. Consult your HELOC agreement for the specific index and reset schedule to understand when and how much your rate may change.
Variable-rate mortgages are less common in the US but matter for those who have them. ARM rates adjust annually or semi-annually depending on the loan terms. Those up for reset in coming months will see higher rates applied to outstanding balances.
What This Means for Savers
The rate increase can benefit savings accounts and money market funds over time. Banks may raise yields on high-yield savings accounts as market competition adjusts. New certificates of deposit issued after a rate increase may offer higher yields to attract deposits. Existing fixed-rate CDs are unaffected.
The Inflation Picture
The Fed’s action reflects persistent inflation that has not responded as expected to previous rate holds. The September decision signals that policymakers determined additional tightening was warranted based on incoming economic data. Variable-rate borrowers and those seeking new credit should account for higher borrowing costs. Consumers with existing fixed-rate obligations are protected from the immediate impact.
Priority question
How much did the Fed raise interest rates?
The Federal Reserve increased its benchmark interest rate by a quarter-point (0.25%) at its September 2026 meeting. This marks the first increase since July 2023. The federal funds target range moves to 3.75%–4.00%.
Closure: The Fed’s September decision introduces new dynamics for borrowers with variable-rate debt. The pace of future increases will depend on economic projections released alongside the September statement. Check your loan documents to understand when and how your specific rates may adjust.