 Sunita Somvanshi
Update, October 5, 2026: Donald Trump has confirmed the US will not impose a diesel export ban following a deal with G7 allies. This article covers the market consequence. [Karmactive previously reported on the original export-ban threat and the initial price spike on October 2 and October 3.]
The threat is gone. The price relief it is producing may be temporary.
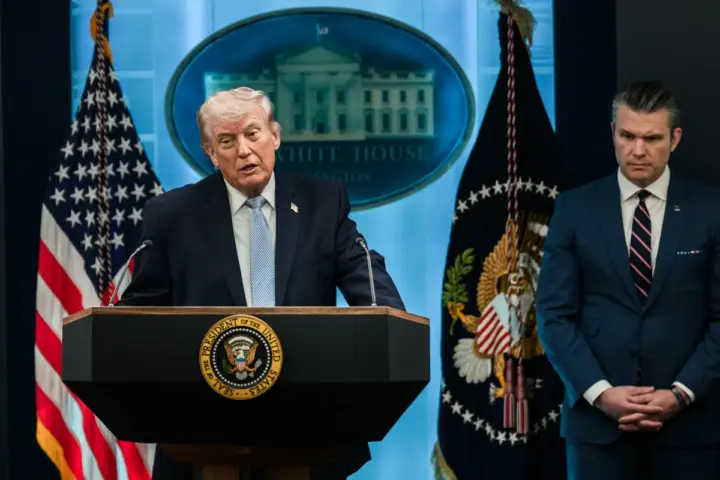
Donald Trump confirmed this week that the United States will not implement a ban on diesel exports to Europe, resolving the most acute phase of a transatlantic fuel standoff that drove diesel price anxiety across UK, EU, and US markets since late September. The decision came after European governments and G7 allies agreed to release 100 million barrels of emergency petroleum reserves — including refined diesel stocks — to offset the supply shortfall that made the export ban politically viable in the first place.
While Trump's withdrawal of the export ban averts an immediate diesel shortage across Europe and the UK, commercial transport operators should not expect long-term price relief. Tapping emergency reserves is lowering pump prices in the near term, but depleting strategic stockpiles leaves refiners with tighter inventories entering winter, meaning a cold snap could trigger sharp, buffered price surges.
Trump stated directly: "We're not going to be doing the export ban… Europe stepped up to release their reserves."
What Actually Changed — and What Didn't
The G7 reserve release matters more than it sounds on first reading because it includes refined products, not just crude. That is the specific detail that moved markets. Adding crude to supply lowers input costs for refineries over weeks; releasing diesel directly into the physical market addresses product shortages in days.
ING's commodities research, published October 5, shows that middle distillate crack spreads — the margin refineries earn by turning crude oil into diesel — have weakened sharply since the reserve release was announced. When crack spreads fall, refiners earn less per barrel of diesel they produce. If margins continue compressing, some European refinery operators may cut run rates, reducing the very product they were just told to produce more of.
This follows Karmactive’s coverage of the G7 Orders 100 Million Barrel Emergency Oil Release and the earlier Diesel at $6.53: Trump Threatens Export Ban Unless Europe Releases Emergency Stocks.
For logistics operators and fleet managers in the UK and EU, the immediate practical outcome is a temporary easing at the pump. UK diesel prices had been elevated against seasonal averages for most of September. Some moderation is now moving through the pricing chain.
The structural risk sits further ahead. European emergency reserves operate under IEA rules that require member states to maintain a 90-day net import cushion at all times. Drawing down those stocks to the levels being discussed in the current release will leave physical inventory buffers thinner than usual as winter heating demand accelerates. If temperatures in northern and central Europe run below historical averages between November and February — which long-range forecasts currently do not rule out — physical diesel markets could re-tighten sharply with reduced buffer.
A related report on Trump Tells Ukraine to Stop Russian Diesel Strikes also showed how diesel supply risks had already moved across the US-Europe policy agenda.
What UK and US Operators Should Watch
The current softening in crack spreads is supply-release driven rather than demand-driven, which means it will reverse when the released volumes clear the market. Operators running on tight fuel margins should assess their exposure to price volatility as the released volumes work through the market.